

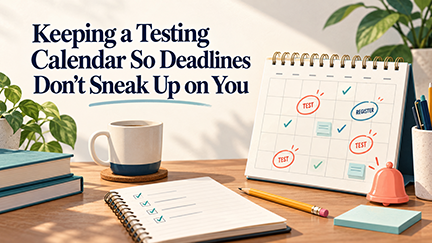
A testing calendar does not replace technical administration, but it can make a business owner’s compliance responsibilities more visible. In the October compliance countdown, a calendar brings together recurring requests, decisions, and reviews that otherwise arrive as isolated emails from payroll, a recordkeeper, or a third-party administrator.
A calendar is a coordination tool.
The best testing calendar is not necessarily complicated. It should show the events that require sponsor attention, the data needed for each event, the people responsible, and the expected handoff date. That may include census collection, ownership updates, payroll reconciliation, preliminary testing, final testing, and follow-up items. The purpose is to create a shared operating rhythm.
A calendar also makes dependencies easier to see. A testing report cannot be fully reviewed until the data file is complete, and a correction cannot be processed until the necessary analysis and approvals are in place. Listing the sequence helps the sponsor recognize where an early request or an internal delay could affect later work.
Build around the plan’s actual data cycle.
Generic reminders can be a starting point, but each organization has its own payroll schedule, bonus timing, workforce changes, and service-provider deadlines. A useful calendar reflects those realities. For example, a business with substantial year-end bonuses may need a separate checkpoint to ensure the right payroll information reaches the plan administrator.
It can be helpful to record both the external deadline and an earlier internal target. The internal date gives payroll, human resources, and finance enough room to resolve questions without treating the provider’s request date as the first possible action date. That buffer is a process safeguard, not a prediction about a particular testing result.
Assign ownership, not just dates.
A deadline on a calendar has limited value if no one knows who will provide the information or approve the next step. For each entry, identify a primary internal owner, a backup contact, the service provider involved, and the records expected. This is particularly useful when the business owner delegates day-to-day plan work but retains governance responsibility.
The calendar can also distinguish between information to provide, information to review, and decisions to document. This prevents an email requesting data from being mistaken for an approval request. Clear labels help the sponsor preserve an audit trail and reduce the chance that a key question is overlooked during a busy period.
Review the calendar after each cycle.
Revise the testing calendar based on experience. If payroll data arrived late, a provider needed an additional report, or a workforce change created unexpected questions, note it for the next cycle. Over time, the calendar becomes a practical record of the plan’s recurring administrative needs.
The annual review is also a suitable time to ask service providers whether their deadlines, file requirements, or contact procedures have changed. A calendar that reflects current responsibilities is more useful than one copied forward without discussion.
Questions to carry into the next review
The most useful follow-up to a discussion of keeping a testing calendar so deadlines don't sneak up on you is a short, repeatable set of questions. What facts changed during the year? Which data sources did the team rely on? Who confirmed the information, and where is the final record kept? These questions are intentionally practical. They help a sponsor distinguish between an issue that needs immediate professional attention and a process item to improve before the next annual cycle.
It can be helpful to include the people closest to the work without expanding sensitive information unnecessarily. Payroll can explain how compensation and elections are processed, human resources can confirm employment events and eligibility records, and the plan administrator can explain the effect of those facts under the document and applicable requirements. The business owner or committee can then focus on oversight: confirming that questions were answered, decisions were documented, and responsibilities were assigned.
Finally, keep the review proportionate. A concise meeting note, the reports considered, and a clear list of follow-up items are often more useful than an informal exchange that cannot be reconstructed later. This approach does not guarantee a particular result, and it does not replace legal, tax, or administrative advice. It does create a dependable governance habit: identify the question, obtain appropriate input, carry out agreed actions, and check the process again as the plan and business evolve.
The same discipline can make service-provider conversations more efficient. Sending a short agenda and relevant records before a meeting gives the administrator or advisor a chance to identify missing facts and prepare a focused explanation. Afterward, the sponsor can circulate only the tasks that each internal owner needs to complete. This keeps plan governance connected to everyday business operations while respecting the dedicated roles of payroll, legal, tax, and retirement-plan professionals. Over time, this record of questions and finished tasks can be a useful reference when the business experiences a staffing change, a new provider relationship, or another event that affects plan administration. Consistently applying this approach can also make annual reviews calmer, more focused, and easier to document. It gives the sponsor a practical reference point to confirm that administrative commitments, provider requests, and internal approvals stay aligned throughout the plan year.
A practical process for plan sponsors
- 1. List every recurring testing-related request, review, and decision in a single annual calendar, beginning with data collection and ending with final documentation.
- 2. For each item, add the provider deadline, an earlier internal target date, the records needed, and the internal person responsible for completing the task.
- 3. Schedule brief check-ins before major handoffs, especially before preliminary testing and final year-end data submission. Use the check-ins for identifying missing information and unusual events.
- 4. After the cycle is complete, record what caused delays or extra questions. Update the next calendar while the process is still fresh and share it with the people who support plan administration.
A testing calendar makes compliance work into a manageable series of conversations and handoffs. By using it consistently and improving it after each cycle, plan sponsors can create better visibility, clearer accountability, and stronger habits for ongoing governance.
Want help building a testing calendar for your plan?
Duncan Williams Asset Management can help you identify the governance checkpoints worth working with your service providers. Duncan Williams Asset Management can help you walk through testing calendars, understand the questions to ask your service providers, and pinpoint areas where additional professional input may be useful. To discuss your plan's annual testing schedule, call our team at 901.435.4250 to arrange a conversation about your retirement plan.
Sources & further reading
- • Internal Revenue Service — 401(k) Plan Fix-It Guide: ADP and ACP Nondiscrimination Tests: https://www.irs.gov/retirement-plans/401k-plan-fix-it-guide-the-plan-failed-the-401k-adp-and-acp-nondiscrimination-tests
- • Internal Revenue Service — Is My 401(k) Top-Heavy?: https://www.irs.gov/retirement-plans/is-my-401k-top-heavy
- • Internal Revenue Service — Fixing Common Plan Mistakes: Top-Heavy Errors: https://www.irs.gov/retirement-plans/fixing-common-plan-mistakes-top-heavy-errors-in-defined-contribution-plans
- • Internal Revenue Service — Retirement Plan Correction Program FAQs: https://www.irs.gov/retirement-plans/retirement-plans-faqs-regarding-governmental-plans-and-epcrs
Disclosure


Recent Articles

Let's talk about your future.
Connect with a local Duncan Williams Asset Management advisor

5350 Poplar Ave.
Suite 600
Memphis, TN 38119

