

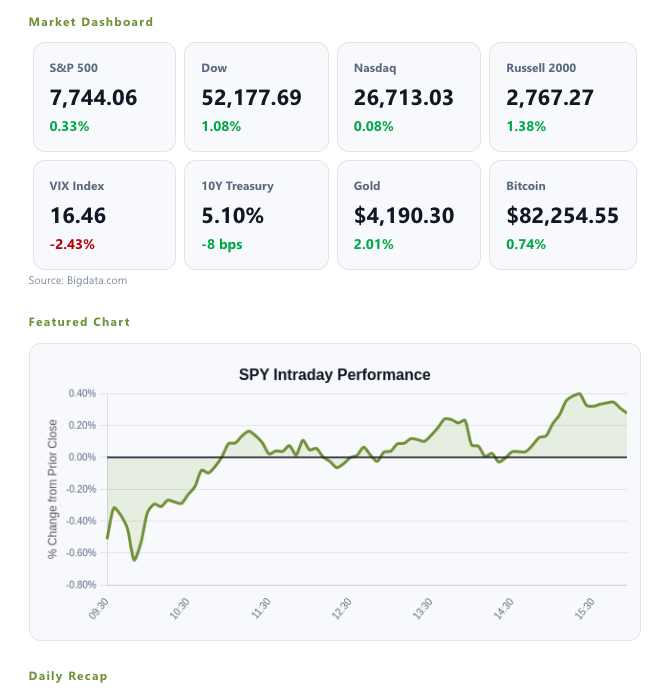
After a shaky, tech-led open, US equities finished higher as a late slide in Treasury yields steadied risk appetite: the Dow led, the S&P 500 eked out gains, and the Nasdaq hovered near flat. The bid broadened outside of mega-cap tech even as producer prices and retail sales surprised on the hot side.
Key Headlines & Market Movers
Rates relief flips the tape: Treasury yields fell hard into the afternoon—the 10-year dropped roughly a tenth of a percentage point—taking pressure off multiples and helping stocks recover from early losses. Participation broadened, with most sectors finishing higher; healthcare, materials, financials and consumer discretionary led while energy, tech and utilities lagged. The rates move helped the Dow post a solid gain, pulled the S&P 500 back to green, and left the Nasdaq near unchanged by the close.
Hot PPI, gas-boosted retail send a mixed macro signal: Wholesale inflation accelerated more than expected in September, with producer prices jumping 1.3% on the month and 6.3% year over year—the fastest since 2022. Retail sales also beat, though much of the strength came from higher gasoline spending, and the core ‘control group’ barely advanced. The combination keeps “higher-for-longer” worries alive even as falling yields spurred a relief rally across most groups.
AI hangover keeps pressure on chips, but losses ease: An AI financing/profitability scare kept tech choppy through the morning before cooler rates helped sentiment. The Philadelphia Semiconductor Index fell more than 4% intraday but closed under 1% lower, and the Nasdaq finished near flat as broader buying returned. Rotation into healthcare and other steadier pockets remained evident into the close.

Into the next few sessions, watch whether yields continue to ease and whether earnings can validate guidance after the AI wobble. Semis’ tone will be a tell for risk appetite, while management commentary on capex and signs of consumer strength beyond gas will shape whether today’s broadening can stick.
Disclaimer
Duncan Williams Asset Management is an SEC registered investment adviser. SEC registration does not constitute an endorsement of Duncan Williams Asset Management by the SEC nor does it indicate that Duncan Williams Asset Management has attained a particular level of skill or ability.
This material prepared by Duncan Williams Asset Management is for informational purposes only and is accurate as of the date it was prepared. It is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation of any particular security, strategy or investment product. Past performance is not indicative of future results. Investing involves risks, including the risk of loss of principal. Before making any investment decision, investors should consult with their financial advisor, consider their individual financial circumstances, and carefully review all relevant information and risk factors. Duncan Williams Asset Management assumes no responsibility for errors or omissions, nor does it accept liability for any loss arising from reliance on this information.
Advisory services are only offered to clients or prospective clients where Duncan Williams Asset Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Duncan Williams Asset Management unless a client service agreement is in place.
This material is not intended to serve as personalized tax, legal and/or investment advice since the availability and effectiveness of any strategy is dependent upon your individual facts and circumstances. Duncan Williams Asset Management is not a legal or accounting firm. Please consult with your legal or tax professional regarding your specific tax situation when determining if any of the mentioned strategies are right for you.
Investment Management Group (IMG)
The Investment Management Group at Duncan Williams Asset Management is led by a team with extensive experience in investment management, financial planning, and client service. President David Scully, CFA®, CFP®, has more than 20 years of experience and is active in Memphis civic organizations. Chief Investment Officer Kyle Gowen, CFA®, CFP®, oversees investment strategy and is engaged with the local community. Investment Analyst Jack Eason, CFA®, provides research and supports charitable initiatives. The IMG team is committed to professional standards, client service, and community involvement. No statement is intended as an offer of investment advice or a guarantee of future results.


Recent Articles

Let's talk about your future.
Connect with a local Duncan Williams Asset Management advisor

5350 Poplar Ave.
Suite 600
Memphis, TN 38119

