

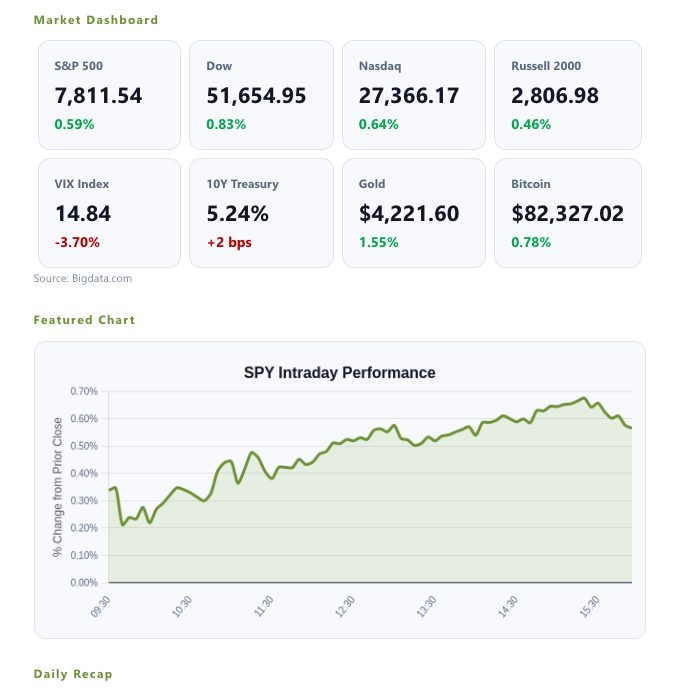
U.S. equities finished higher, recouping part of Thursday’s AI-led selloff. The Dow, S&P 500, and Nasdaq each rose around two‑thirds of a percent, with the S&P back near record territory as gains broadened beyond mega‑cap tech. Oil prices eased and long‑term Treasury yields held near—but a touch off—recent highs, setting the stage for bank earnings next week.
Key Headlines & Market Movers
AI jitters fade after Thursday’s tech swoon: Thursday’s downdraft centered on AI and chip shares after reports suggested OpenAI’s annualized revenue is closer to $50B than prior expectations, pressuring the broader AI buildout and semiconductors. Futures and cash markets showed a modest rebound today, with the Nasdaq participating as nerves settled and dip‑buyers tested the waters. Importantly, breadth improved versus the narrow leadership that’s dominated for weeks, a constructive sign for durability of the rally. Still, concentration risk lingers if mega‑cap earnings or AI demand narratives stumble.
Rates remain a headwind, but a slight intraday ease helped risk appetite:Long‑end Treasury yields remain elevated near cycle highs, a backdrop that keeps a lid on valuation expansion and tightens financial conditions. Yields edged off recent peaks into the afternoon, removing some pressure and giving equities room to firm. The push‑and‑pull between higher‑for‑longer policy expectations and resilient growth remains the core macro tug‑of‑war. With that mix, defensive quality continues to find sponsorship while investors selectively add cyclicals on pullbacks.
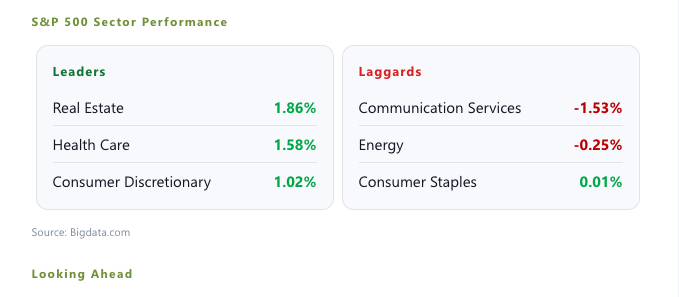
Oil cools; rotation peeks through beyond mega‑cap tech: Crude prices eased after a volatile stretch, softening near‑term inflation anxiety and aiding sentiment. This week’s leadership broadened beyond tech, with defensives and energy among relative winners, a sign investors are seeking balance as yields stay high. Today’s bounce saw more sectors participate, helping the S&P 500 edge back toward highs even as AI narratives recalibrate. Into earnings, that broadening matters more than any single headline.
Next week brings the first major bank reports—watch loan growth, deposit costs, and credit trends—for read‑throughs on the consumer and funding. Mid‑week inflation data will shape rate expectations; if long yields stay contained, breadth could hold and support the tape. Key tell: whether semis and AI‑linked names stabilize while defensives keep a bid.
Disclaimer
Duncan Williams Asset Management is an SEC registered investment adviser. SEC registration does not constitute an endorsement of Duncan Williams Asset Management by the SEC nor does it indicate that Duncan Williams Asset Management has attained a particular level of skill or ability.
This material prepared by Duncan Williams Asset Management is for informational purposes only and is accurate as of the date it was prepared. It is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation of any particular security, strategy or investment product. Past performance is not indicative of future results. Investing involves risks, including the risk of loss of principal. Before making any investment decision, investors should consult with their financial advisor, consider their individual financial circumstances, and carefully review all relevant information and risk factors. Duncan Williams Asset Management assumes no responsibility for errors or omissions, nor does it accept liability for any loss arising from reliance on this information.
Advisory services are only offered to clients or prospective clients where Duncan Williams Asset Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Duncan Williams Asset Management unless a client service agreement is in place.
This material is not intended to serve as personalized tax, legal and/or investment advice since the availability and effectiveness of any strategy is dependent upon your individual facts and circumstances. Duncan Williams Asset Management is not a legal or accounting firm. Please consult with your legal or tax professional regarding your specific tax situation when determining if any of the mentioned strategies are right for you.
Investment Management Group (IMG)
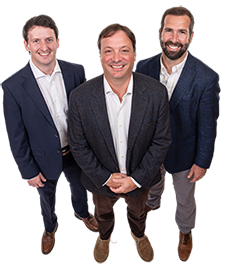
The Investment Management Group at Duncan Williams Asset Management is led by a team with extensive experience in investment management, financial planning, and client service. President David Scully, CFA®, CFP®, has more than 20 years of experience and is active in Memphis civic organizations. Chief Investment Officer Kyle Gowen, CFA®, CFP®, oversees investment strategy and is engaged with the local community. Investment Analyst Jack Eason, CFA®, provides research and supports charitable initiatives. The IMG team is committed to professional standards, client service, and community involvement. No statement is intended as an offer of investment advice or a guarantee of future results.


Recent Articles

Let's talk about your future.
Connect with a local Duncan Williams Asset Management advisor

5350 Poplar Ave.
Suite 600
Memphis, TN 38119

