

Stocks climb as cooler jobs tilt Fed calculus; tech and consumer names lead while energy slips
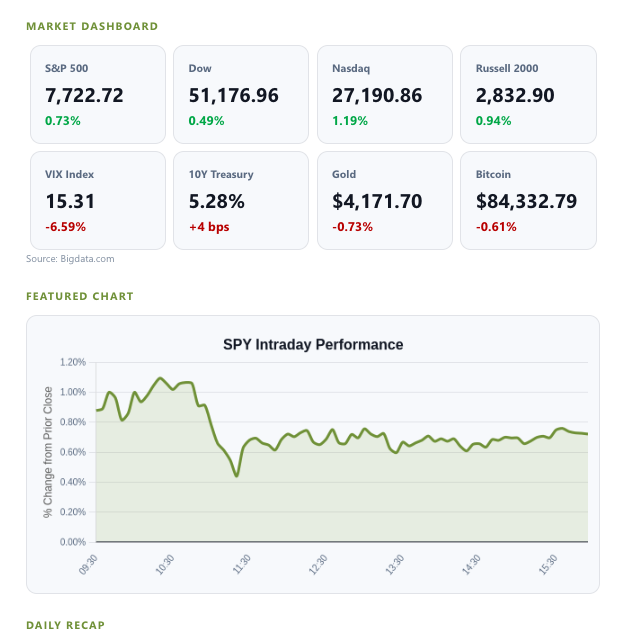
Equities pushed higher after a softer September payrolls print eased fears of another near‑term rate hike, helping growth stocks regain their footing. Yields and the dollar faded from recent highs, oil retreated, and leadership rotated back to tech and consumer discretionary while defensives and energy lagged.
KEY HEADLINES & MARKET MOVERS
Jobs report cools, rates ease, risk appetite returns: Payroll growth slowed to roughly a third of expectations and prior months were revised lower, a combination that nudged investors toward a gentler Fed path. The unemployment rate ticked up and wage gains moderated, reinforcing the “cooling, not collapsing” labor narrative. Treasury yields drifted down from recent peaks and the dollar slipped below a key threshold as rate‑hike odds fell, a backdrop that favored duration‑sensitive equities.
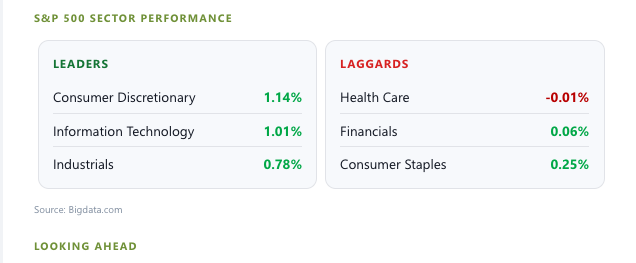
Leadership swings back to growth; energy under pressure as oil slides: Most sectors finished in the green with tech and consumer discretionary pacing gains, a setup consistent with easing rate pressure and firmer risk appetite. Energy lagged as crude fell sharply, reflecting softer demand concerns and the reset in growth expectations. The tone marked a reversal from recent sessions dominated by rising yields and commodity strength.
Dealmaking and single‑name moves add fuel: An all‑cash agreement by onsemi to acquire Synaptics buoyed chip and AI‑adjacent sentiment, while select consumer and hardware names diverged on company‑specific news. Nike traded lower on a cautious multi‑year profit outlook, and hard‑disk suppliers slid on reports of capacity expansion from a key competitor. The mix underscored that macro tailwinds helped, but idiosyncratic stories still drove dispersion beneath the surface.
Attention turns to the Fed next week: with labor cooling and inflation mixed, markets will watch whether policymakers lean into a pause and how they frame the path ahead; keep an eye on whether Treasury yields stabilize, the dollar’s pullback persists, and if oil’s slide extends—each will shape whether today’s growth‑led bias can stick.
Disclaimer
Duncan Williams Asset Management is an SEC registered investment adviser. SEC registration does not constitute an endorsement of Duncan Williams Asset Management by the SEC nor does it indicate that Duncan Williams Asset Management has attained a particular level of skill or ability.
This material prepared by Duncan Williams Asset Management is for informational purposes only and is accurate as of the date it was prepared. It is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation of any particular security, strategy or investment product. Past performance is not indicative of future results. Investing involves risks, including the risk of loss of principal. Before making any investment decision, investors should consult with their financial advisor, consider their individual financial circumstances, and carefully review all relevant information and risk factors. Duncan Williams Asset Management assumes no responsibility for errors or omissions, nor does it accept liability for any loss arising from reliance on this information.
Advisory services are only offered to clients or prospective clients where Duncan Williams Asset Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Duncan Williams Asset Management unless a client service agreement is in place.
This material is not intended to serve as personalized tax, legal and/or investment advice since the availability and effectiveness of any strategy is dependent upon your individual facts and circumstances. Duncan Williams Asset Management is not a legal or accounting firm. Please consult with your legal or tax professional regarding your specific tax situation when determining if any of the mentioned strategies are right for you.
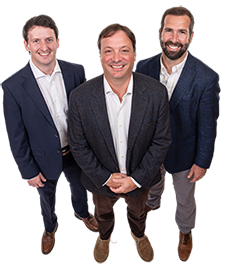
Investment Management Group (IMG)
The Investment Management Group at Duncan Williams Asset Management is led by a team with extensive experience in investment management, financial planning, and client service. President David Scully, CFA®, CFP®, has more than 20 years of experience and is active in Memphis civic organizations. Chief Investment Officer Kyle Gowen, CFA®, CFP®, oversees investment strategy and is engaged with the local community. Investment Analyst Jack Eason, CFA®, provides research and supports charitable initiatives. The IMG team is committed to professional standards, client service, and community involvement. No statement is intended as an offer of investment advice or a guarantee of future results.


Recent Articles

Let's talk about your future.
Connect with a local Duncan Williams Asset Management advisor

5350 Poplar Ave.
Suite 600
Memphis, TN 38119

