

Stocks soften as yields firm and confidence slips; oil cools, energy lags
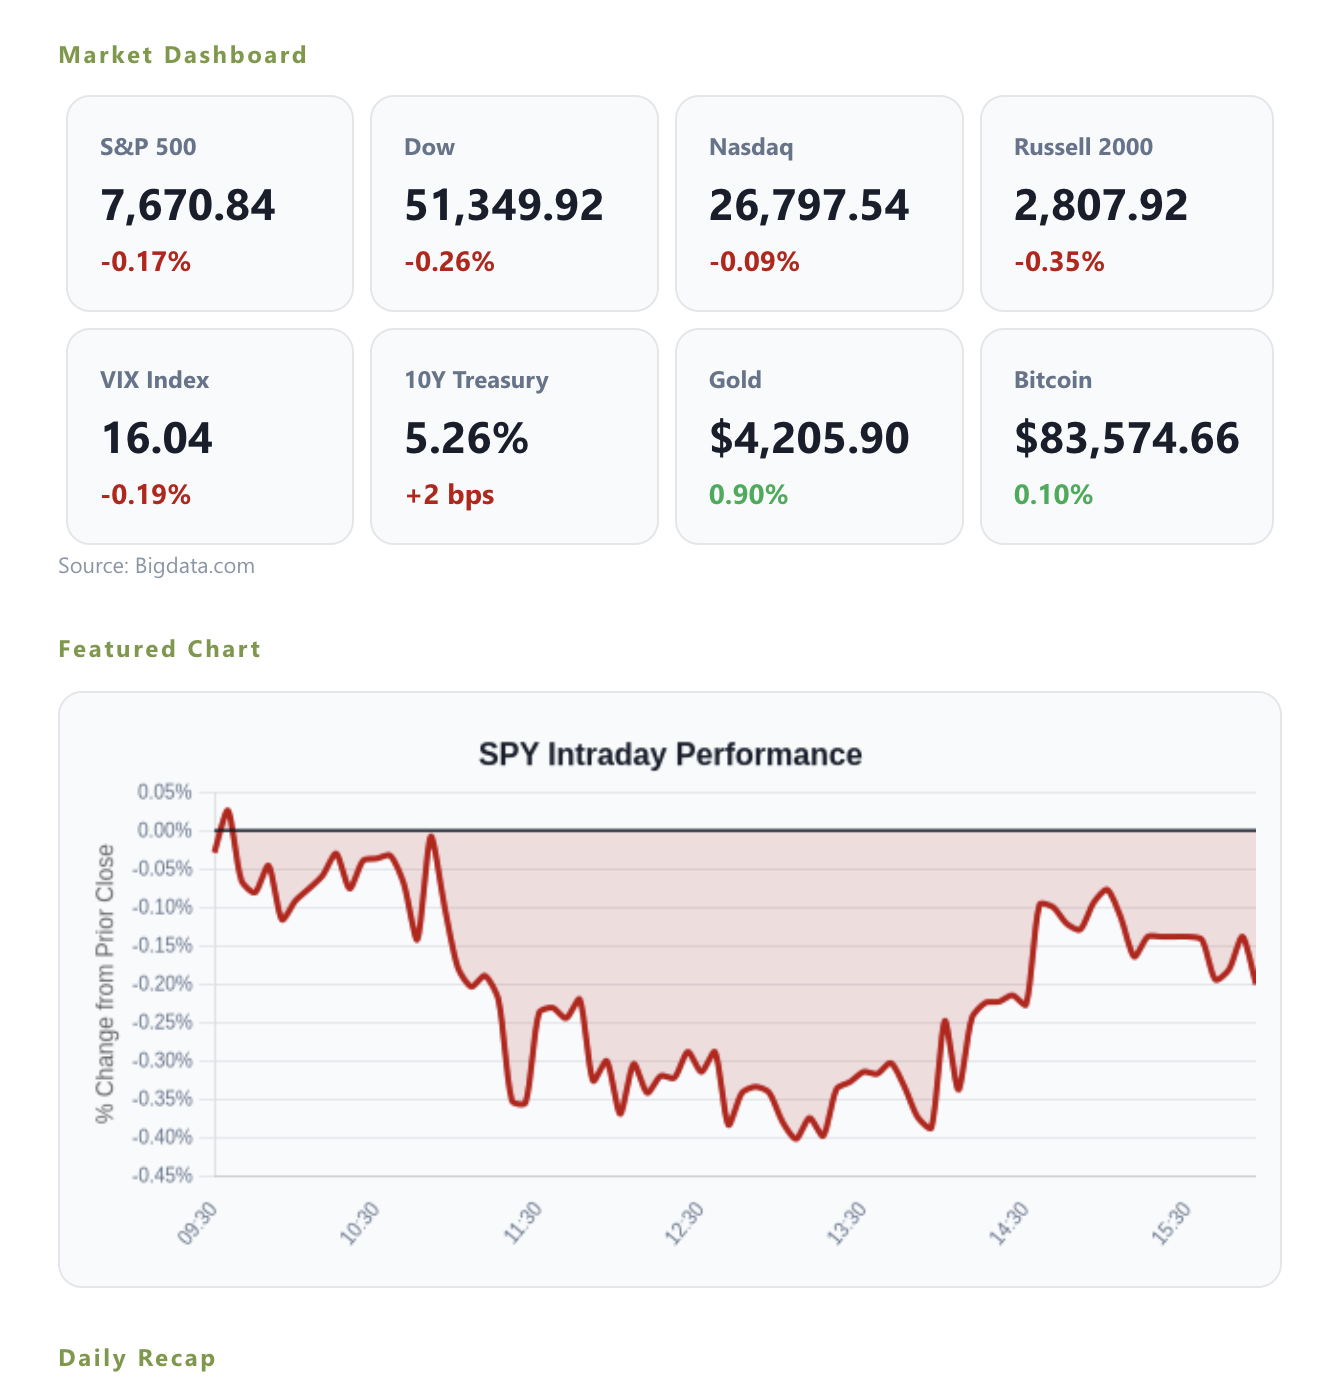
U.S. equities finished mixed-to-lower as a fresh rise in Treasury yields and a drop in consumer confidence to the weakest since 2014 kept buyers cautious. Oil eased, taking some heat off broader inflation worries, but energy shares underperformed while megacap tech steadied the tape. Investors also weighed softer job openings as the market’s focus rotated back to the growth–rates trade-off.
Key Headlines & Market Movers
Rates and sentiment set the tone: Long-end yields pushed higher again, tightening financial conditions and pressuring cyclicals intraday. At the same time, the Conference Board’s gauge of consumer confidence fell to its lowest level since 2014, reinforcing a cautious read on household demand. Job openings eased, consistent with a cooling—but not collapsing—labor market backdrop that has characterized much of this year. Together, the mix kept dip-buying selective and skewed toward balance-sheet strength.
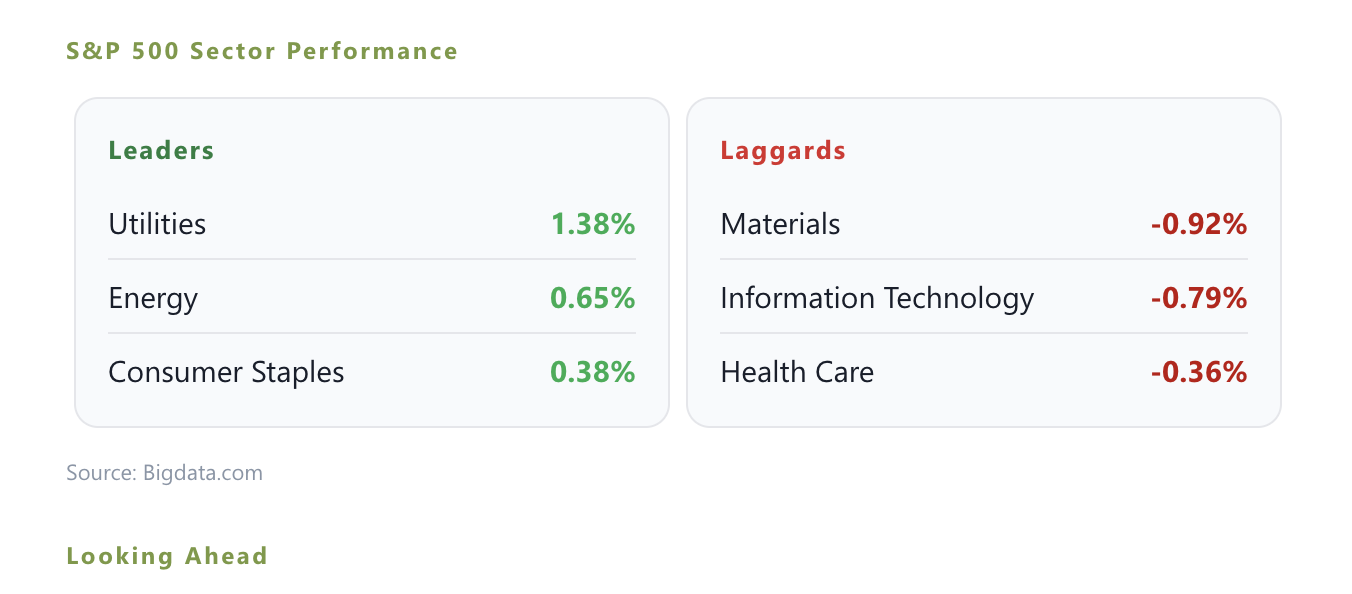
Oil cools, energy trails despite a brief relief on inflation optics: Crude prices slipped, offering a modest counter to inflation anxiety even as rates stayed elevated. The move wasn’t enough to lift energy shares, which led sector laggards as investors faded recent strength tied to supply concerns. With oil still volatile, equity positioning remained defensive around the edges while leadership concentrated in larger, cash-rich platforms.
Company tape: resilient consumer pockets, selective listings window: CarMax rallied after posting stronger sales and profit, a sign that targeted value offerings can still find demand in a higher-rate world. Carnival topped expectations and lifted its outlook, underscoring ongoing travel normalization and cost discipline. In contrast, smart-ring maker Oura postponed its planned IPO, reflecting a still fragile window for new issuance despite isolated strength in marquee names.
Attention turns to labor and inflation updates later this week; watch whether long-end yields pause or extend higher, as that path likely dictates risk appetite more than any single print. Oil’s next swing will shape the inflation narrative at the margin, while in equities, breadth remains the tell—can leadership broaden beyond a handful of megacaps or will defensiveness persist.
Disclaimer
Duncan Williams Asset Management is an SEC registered investment adviser. SEC registration does not constitute an endorsement of Duncan Williams Asset Management by the SEC nor does it indicate that Duncan Williams Asset Management has attained a particular level of skill or ability.
This material prepared by Duncan Williams Asset Management is for informational purposes only and is accurate as of the date it was prepared. It is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation of any particular security, strategy or investment product. Past performance is not indicative of future results. Investing involves risks, including the risk of loss of principal. Before making any investment decision, investors should consult with their financial advisor, consider their individual financial circumstances, and carefully review all relevant information and risk factors. Duncan Williams Asset Management assumes no responsibility for errors or omissions, nor does it accept liability for any loss arising from reliance on this information.
Advisory services are only offered to clients or prospective clients where Duncan Williams Asset Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Duncan Williams Asset Management unless a client service agreement is in place.
This material is not intended to serve as personalized tax, legal and/or investment advice since the availability and effectiveness of any strategy is dependent upon your individual facts and circumstances. Duncan Williams Asset Management is not a legal or accounting firm. Please consult with your legal or tax professional regarding your specific tax situation when determining if any of the mentioned strategies are right for you.
Investment Management Group (IMG)
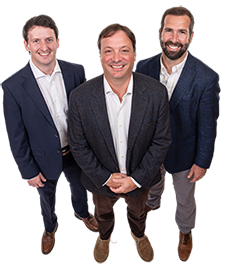
The Investment Management Group at Duncan Williams Asset Management is led by a team with extensive experience in investment management, financial planning, and client service. President David Scully, CFA®, CFP®, has more than 20 years of experience and is active in Memphis civic organizations. Chief Investment Officer Kyle Gowen, CFA®, CFP®, oversees investment strategy and is engaged with the local community. Investment Analyst Jack Eason, CFA®, provides research and supports charitable initiatives. The IMG team is committed to professional standards, client service, and community involvement. No statement is intended as an offer of investment advice or a guarantee of future results.


Recent Articles

Let's talk about your future.
Connect with a local Duncan Williams Asset Management advisor

5350 Poplar Ave.
Suite 600
Memphis, TN 38119

